
Sportradar's history is not simply the story of a company buying other companies. It is a record of how a sports-data business assembled software, video analysis, betting technology and valuable distribution rights - and how it subsequently began deciding which pieces belonged together.
The business traces its origins to 2001. The listed Swiss parent, Sportradar Group AG, was incorporated on 24 June 2021, before Sportradar shares began trading on Nasdaq on 14 September 2021. Its most significant recent transaction, the IMG ARENA acquisition, closed in November 2025. By contrast, the announced US$170 million sale of Atrium Sports' coaching and scouting business was still a proposed transaction in Sportradar's 3 November 2026 financial update, with completion expected in the fourth quarter subject to conditions.
For the group's wider context, start with our Sportradar corporate overview.
From a 2001 sports-data business to a listed Swiss group

Sportradar developed at the intersection of sport and information. Its customers came to include bookmakers, media businesses, sports organisations and technology providers that needed structured, timely data or tools built around it. Such customers are not, merely by being customers or commercial partners, subsidiaries of Sportradar.
The corporate genealogy is especially important when reading old filings. Sportradar AG is not interchangeable with Sportradar Group AG, the parent whose Class A shares trade under SRAD. The latter was incorporated in Switzerland on 24 June 2021 as part of the pre-IPO structure. The existing operating business did not suddenly begin in that year: it was reorganised into a listed group with an established commercial history.
The important dates - and what actually changed
| Date | Event | Transaction status and significance |
|---|---|---|
| 2001 | Sportradar business origins | Historical start of the business, not incorporation of the later listed parent. |
| 24 June 2021 | Sportradar Group AG incorporated | Formation of the Swiss listed-company parent ahead of the IPO. |
| 14 September 2021 | Nasdaq trading begins | Public-market milestone under ticker SRAD. |
| 2021-2022 | Fresh Eight, Atrium, Interact, VAIX, Ortec and increased NSoft control | Acquisitions and control changes added advertising, analysis, video and betting-related technology. |
| 2023 | BetTech and Interact Sport disposals | Completed exits from particular businesses, not a group-wide retreat from sports data. |
| 13 November 2024 | US affiliate assets of XLMedia acquired | Asset/business acquisition rather than purchase of the entire listed XLMedia group. |
| 19 March-3 November 2025 | IMG ARENA transaction | Signed, competition-cleared and subsequently completed, with unusual financial support from the seller. |
| 7 October 2026 | Agreement to divest Atrium coaching/scouting business | Agreed, not confirmed completed in the 3 November 2026 results; US$170 million proposed cash price. |
Sportradar's 2021 Nasdaq IPO: price and restructuring

Sportradar's IPO was priced on 13 September 2021 at US$27 per Class A ordinary share, with 19 million shares in the offering. Trading started on Nasdaq the following day. Multiplying the advertised offer size by the offer price gives approximately US$513 million in gross offering value before underwriting costs and other distinctions in the allocation of shares. It would be wrong to label that calculation the company's net cash proceeds.
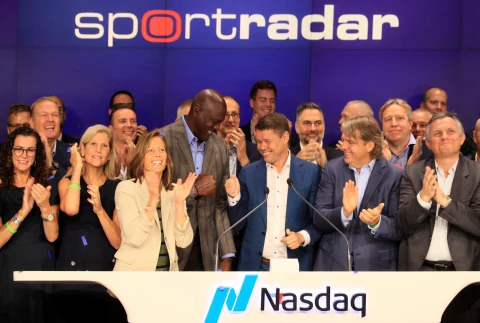
The 2021 listing should also be distinguished from a much earlier financial-news headline about a US$100 million placeholder in a registration filing. An initial filing amount is not the final offer size or the amount raised after pricing. Equally, the IPO's market valuation is not the purchase price of any business the company had acquired.
The listing made the existing acquisition strategy more visible through public financial disclosures. The share structure and subsequent market performance belong in our Sportradar shares and chart analysis.
The 2021 acquisitions: Fresh Eight, Atrium and Interact

Three purchases illustrate what Sportradar was building before and around its Nasdaq debut. They involved different markets and functions; calling each one simply a sports-data acquisition would obscure the point.
Fresh Eight Limited - acquired 2 March 2021. This UK advertising-technology business specialised in personalised marketing and messaging. The attraction, viewed through Sportradar's wider commercial model, was the ability to use data in advertising and audience engagement rather than merely supply event information. That is a statement about the capability acquired, not proof that any later campaign generated a particular return. A historical acquisition should not be mistaken for a claim that the same UK legal entity or product remains unchanged today.
Atrium Sports Inc - acquired 6 May 2021. Atrium added video-led sports analysis and the coaching-and-scouting technology associated with Synergy Sports. The deal illustrates an expansion towards teams, leagues and performance analysis alongside the bookmaker-facing business. Sportradar's 2023 annual report describes €183.0 million of cash paid as part of the original transaction, with participation certificates also issued. Its reported total consideration transferred of approximately €192.219 million is a broader accounting measure than the cash figure; neither should be silently substituted for the other.
Interact Sport Pty Ltd - acquired 9 June 2021. This Australian cricket technology and data business broadened the group's reach into sport-specific competition and information systems. The 2023 filing describes the purchase of 100% of voting interests and a cash component of approximately €4.7 million, with deferred consideration also relevant to the transaction terms. Interact's subsequent sale is particularly useful evidence that acquisition was not always permanent ownership.
Readers who need the current rather than historical identity of the group's products can use our Sportradar brands and subsidiaries guide. The history here concerns what entered the group, when, and what subsequently left it.
2022-2024: AI acquisitions, control changes and selective exits

The years after the IPO offer a clearer picture of the different instruments Sportradar used. Some deals bought an entire company; one increased an existing stake to a controlling interest; later transactions removed businesses or purchased an operating asset package.
Building tools and taking control
On 6 April 2022, Sportradar acquired VAIX Limited, a technology business focused on artificial-intelligence-driven personalisation in betting and gaming. The 2023 annual report records €21.7 million of cash paid at closing, but its acquisition accounting also contemplated contingent consideration. Reporting the initial cash payment as the complete, unconditional economic cost would therefore be misleading. The strategic proposition was to turn data into more tailored products and customer experiences, although the historical filing does not certify a particular uplift in customer spending.
On 28 April 2022, the group bought Ortec Sports B.V., a provider of analysis tools for teams and federations, for cash consideration reported at approximately €5.7 million. This extended the performance-analysis theme. It also illustrates why acquisitions should not be narrated exclusively as successes: later reporting described parts of the related activity being wound down. Integration and continued investment are decisions, not automatic consequences of an announced deal.
The following day, 29 April 2022, Sportradar acquired a further 30% interest in NSoft, on top of its existing 40%, increasing its ownership to 70% and obtaining control for consolidation purposes. That is different from acquiring a company for the first time. A subsequent FY2025 subsidiary listing reports NSoft at 100%, but the two dated snapshots do not establish precisely when the intervening ownership change occurred. Any claim about a specific intermediate purchase date would need a separate source.
On 12 January 2023, the group acquired Aforoa Ltd, which brought computer-vision capabilities for deriving sports information from video. Its FY2023 filing reports about €4.9 million of cash consideration, with possible contingent payments also relevant. Such tools can support more automated collection and processing of sports data, although the acquisition itself is not evidence of an achieved reduction in every production cost.
The Sportradar business model explains how those tools produce revenue; the deal history explains how they entered the group.
Exiting businesses - and buying a different kind of asset
Two 2023 disposals deserve attention precisely because they are usually missing from headline-driven acquisition timelines.
BetTech was sold on 30 November 2023, with reported disposal consideration of approximately €0.5 million. Its treatment in the annual report involved discontinued operations. The subsidiary's route through an earlier joint-venture relationship makes it a particularly poor candidate for a simple “bought in year X, sold in year Y” profit calculation.
Interact Sport, acquired in 2021, was sold on 30 December 2023 for reported consideration of approximately €0.2 million. The annual report did not treat this disposal as discontinued operations. Those accounting classifications are different even though both assets left the group. Nor does a headline sale consideration alone provide the proceeds-versus-cost analysis needed to judge the economic outcome of the original acquisition.
On 13 November 2024, Sportradar acquired the US gambling affiliate operations of XLMedia. This was an acquisition of an operation or asset package, not a takeover of all of XLMedia PLC. Commercially, affiliate traffic and customer-acquisition technology are closer to distribution and marketing than to ownership of a sports league's official data rights. Treating them as identical inputs would conceal how broad Sportradar's portfolio had become.
I read these smaller deals as evidence of a group refining its portfolio, not as proof of successful investment returns. Those require a separate look at Sportradar financial results.
IMG ARENA acquisition: why the seller provided financial support

The IMG ARENA acquisition is the transaction most likely to be misunderstood in a brief company history. Sportradar announced an agreement on 19 March 2025 to acquire IMG Arena US Parent, LLC and its portfolio of sports betting data and audiovisual rights. It was not an acquisition of OpenBet. The UK's Competition and Markets Authority cleared the anticipated merger on 3 October 2025. Sportradar's FY2025 acquisition accounting uses 1 November 2025 as the acquisition date, while the company publicly announced completion on 3 November 2025.
Unusually, Endeavor's seller-side arrangements provided up to US$225 million of support associated with the business and its rights commitments. Sportradar did not pay Endeavor that amount, nor was all the support transferred directly to Sportradar.
Three dated descriptions of the same US$225 million arrangement
| Source and reporting stage | Support paid or payable to Sportradar | Seller-funded payments towards sports rightsholders |
|---|---|---|
| FY2024 report / March 2025 agreement disclosure | US$125m | Up to US$100m |
| 3 November 2025 official closing announcement | Approximately US$103m, subject to customary purchase-price adjustments | Approximately US$122m |
| FY2025 report / later acquisition accounting disclosure | US$100m, described as two future anniversary instalments | Up to US$125m |
The US$225 million combined headline remains the same, but the allocations differ across the documents. The closing announcement said direct payments would be made over two years and were subject to purchase-price adjustments. I would neither average the three splits nor silently substitute one for another: prepayments to rightsholders and cash receivable by the buyer affect the economics differently.
The FY2025 financial statements add another layer. They report negative acquisition consideration of about €72.358 million, including an approximately €78.388 million fair-value receivable offset by approximately €6.030 million of cash payments. Seller-funded rightsholder prepayments made before the acquisition reduced assumed liabilities and were not booked as purchase consideration. This IFRS measurement is not interchangeable with the US-dollar support headline, the original announced allocation or the eventual operating profit of the rights business.
Sports media rights carry both commercial opportunities and contractual commitments. I interpret the seller support as assistance linked to assuming those commitments, not evidence that the rights were risk-free. The CMA examined competition effects from the deal; its clearance was not a UK gambling operating licence.
IMG ARENA expanded the rights portfolio, but returns depend on demand, utilisation and renewal costs. Our markets, partners and licences analysis examines that commercial context.
The 2026 Synergy/Atrium divestment: what was agreed to be sold

On 7 October 2026, Sportradar announced a definitive agreement to sell Atrium Sports, the coaching and scouting business of Synergy Sports, to Teamworks Innovations, Inc. for US$170 million in cash. This is a proposed disposal of a specified business perimeter, not the announced sale of every Synergy-branded capability and not proof that the deal had closed.
The distinction remained current in the group's 3 November 2026 Q3 results: management said completion was expected in Q4 2026, subject to customary closing conditions, and excluded any anticipated divestment effect from its 2026 guidance because the closing date was uncertain. No later completion announcement was identified in the primary corporate release list consulted for this draft. Accordingly, the defensible status here is agreement signed; closing not independently established as at 13 November 2026.
| Agreed sale perimeter | Capabilities Sportradar said it would retain |
|---|---|
| Atrium Sports' coaching and scouting operation within Synergy Sports, subject to completion | Certain automated video-production cameras, automated graphics, computer-vision capabilities, competition-management products, and related integrated assets and revenue |
This is where the 2021 Atrium acquisition becomes relevant again. Sportradar acquired an entire video-and-analysis business in May 2021 and announced the planned sale of a defined part of that business five years later. The 2021 accounting consideration, reported in euros, includes a different perimeter and instruments from the proposed 2026 dollar cash proceeds. Comparing €192.219 million with US$170 million and calling the difference a gain or loss would ignore currencies, time, retained operations, transaction costs and accounting allocations.
The stated aim was to concentrate on betting, gaming and media without surrendering every video or analytics capability. Whether that improves results cannot be established before completion and subsequent disclosures.
For readers evaluating the commercial and execution uncertainties, our Sportradar risks and opportunities review looks beyond the transaction headlines. For ownership and the people directing the portfolio decisions, consult Sportradar management and ownership.
What Sportradar's deal history reveals

I see three separate phases, although the boundaries overlap. First, Sportradar assembled a broad toolkit around sports information: marketing, AI, video, performance analysis and sport-specific systems. Second, it bought greater scale in audiovisual and betting rights through IMG ARENA, using a transaction structure that cannot be explained by an ordinary buyer-pays-seller headline. Third, it began showing more selective ownership discipline by exiting smaller assets and agreeing to sell the coaching-and-scouting operation while retaining technologies relevant to its core business.
An acquisition is not automatically a success, nor a disposal a failure. The real test is how the changing portfolio affects revenue quality, contractual costs, competition and capital allocation over several reporting periods.
The dates also impose useful limits on interpretation. 2001 marks the origin of the business; 2021 marks the incorporation of its listed parent and the Nasdaq IPO; November 2025 marks completion of the IMG ARENA acquisition; and October 2026 marks an agreement for a narrower Atrium disposal, not a confirmed completed sale in the latest identified primary reporting. Keeping those facts separate produces a more accurate picture than a simple list of companies Sportradar once owned.
For wider comparisons with other major gambling technology businesses, explore the GambleBallers gambling empires directory. The relevant lesson from Sportradar is not the number of transactions: it is how a B2B group's economic perimeter changes when technology, rights and customer-facing services are bought, integrated, retained or sold.